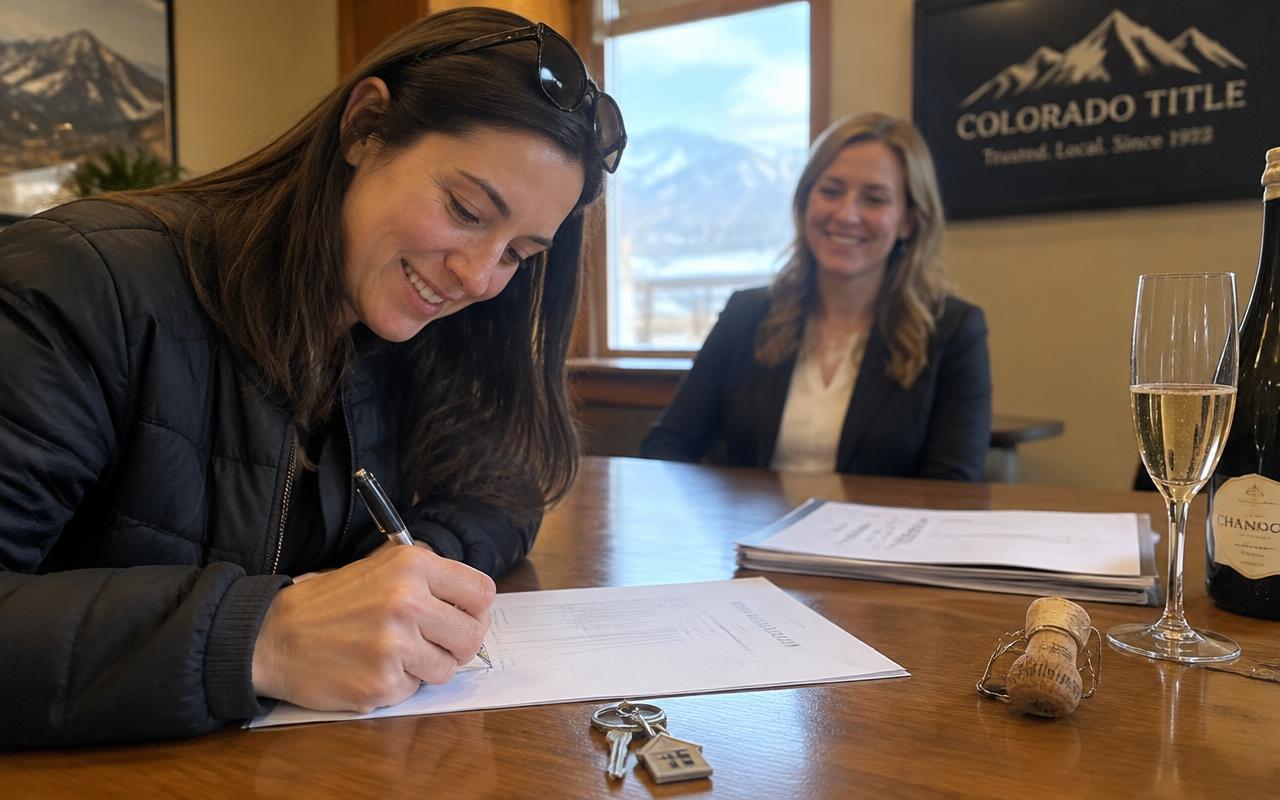Buyer guide

Closing costs in Colorado, explained

How much to expect, what is actually inside the number, and the honest ways to reduce the cash you bring to closing.

A buyer signing closing documents at a Colorado title office with keys on the table

Most Colorado buyers bring somewhere between two and four percent of the purchase price to closing, and a good chunk of that is not fees at all. It is prepaid money that funds your own escrow account.

How much are closing costs in Colorado?

On a 500,000 dollar home, plan on roughly 10,000 to 20,000 dollars in total cash to close beyond the down payment, with the wide end of that range driven mostly by prepaid taxes and insurance. Your actual figure arrives on a Loan Estimate within three business days of application, and it is an estimate you can question line by line.

What is inside the number

Lender charges, such as underwriting and processing, plus the appraisal. Title and settlement charges, including the lender's title policy and the closing itself, which in Colorado usually happens at a title company. County recording fees. And then the prepaids: your first year of homeowner's insurance, property tax deposits, and the initial funding of your escrow account.

Prepaids are the piece that surprises people. That money is not a fee anyone collects; it is your own money, preloaded into the account that pays your taxes and insurance.

Who pays what

Buyers typically pay lender fees, prepaid items, and their own title charges. Sellers typically pay the real estate commissions and their side of the title and transfer charges. Some Colorado municipalities add a small transfer tax, and who covers it is negotiable.

Almost none of that is fixed by law. It is negotiated in the contract, which is why your loan team and your agent need to be talking to each other.

Five honest ways to bring less cash

Ask for a seller credit toward your closing costs, which is most realistic in a balanced market. Use a lender credit, which covers costs in exchange for a rate a step higher; that trade can be worth it if you plan a shorter stay. Ask the seller to pay points that buy your rate down instead. Compare fees, because as a broker we shop your file across more than 70 wholesale mortgage banks. And close near the end of the month to trim prepaid interest.

One caution: the goal is the best overall deal, not the smallest closing page. A lender credit that costs you a much higher rate for thirty years is an expensive favor. We will run the math both ways before you choose.

Down payment and closing costs are separate

Your down payment goes toward the purchase price. Closing costs pay the professionals, the county, and the prepaids. They are separate line items, and assistance programs can cover one, the other, or both.

What buyers ask about closing costs

Questions about your own numbers?

Call or text 720-386-4071, or start the application and we will follow up the same day. The conversation is free, and the math is yours to keep.

Chat Now