Buying a home in Denver
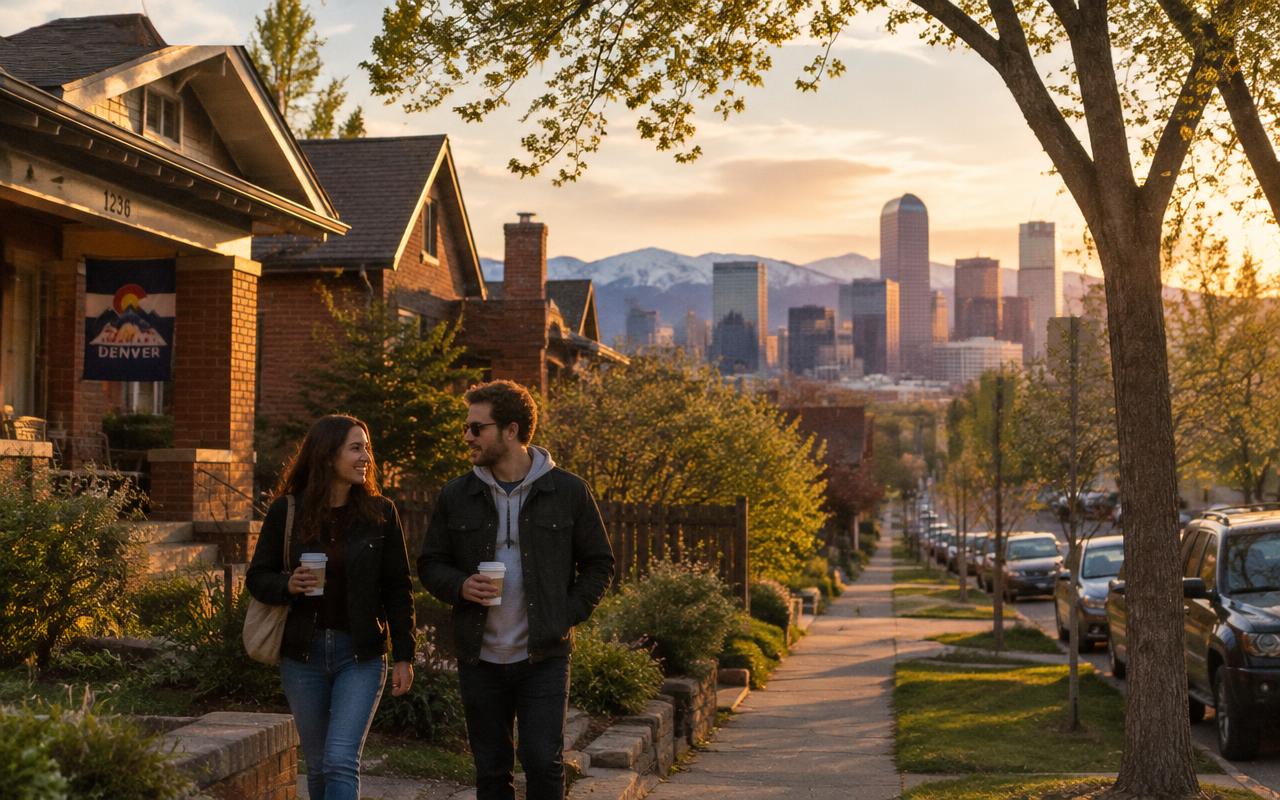
Denver is both a city and a county, so the City and County of Denver handles property taxes, permits, and its own housing programs under one roof. That keeps the paperwork simpler than in suburbs that straddle county lines, but the housing stock is anything but simple. In a single afternoon you can tour a downtown condo, a Sloan's Lake townhome, and a 1920s brick bungalow in Platt Park, and each one gets financed a little differently.
Condos are where Denver files most often get complicated. Before a lender approves the loan, the building itself is reviewed: the HOA budget, reserves, insurance, owner occupancy, and any litigation. A building that fails the agency review can still be financed, just through a different set of lenders. We order the HOA questionnaire early so a surprise does not show up a week before closing.
Older single-family homes bring their own checklist. Sewer line scopes, aging electrical panels, and foundation notes on a 100-year-old house can affect the appraisal and the repair negotiation, so we talk through what an inspection finding means for your loan before you decide how to respond.
When you call us about a Denver home, we start with the property type, because a condo, a townhome, and a century-old bungalow each lead to a different lender shortlist. Then we shop that shortlist across our wholesale lenders so the terms and fees you see are competitive for that specific kind of home.
- Condos and townhomes: Ask for the HOA budget, reserve study, and master insurance policy before you write the offer.
- Older homes: Budget time for a sewer scope and a thorough inspection.
- Assistance: metroDPA, CHFA, and Denver's own homeownership programs each have separate rules, so compare them side by side.