Investor lending

DSCR loans: qualify on the property, not your paperwork

A rental property loan built around the deal in front of you. The home's rent covers the payment, and your tax returns stay where they belong, in a drawer.

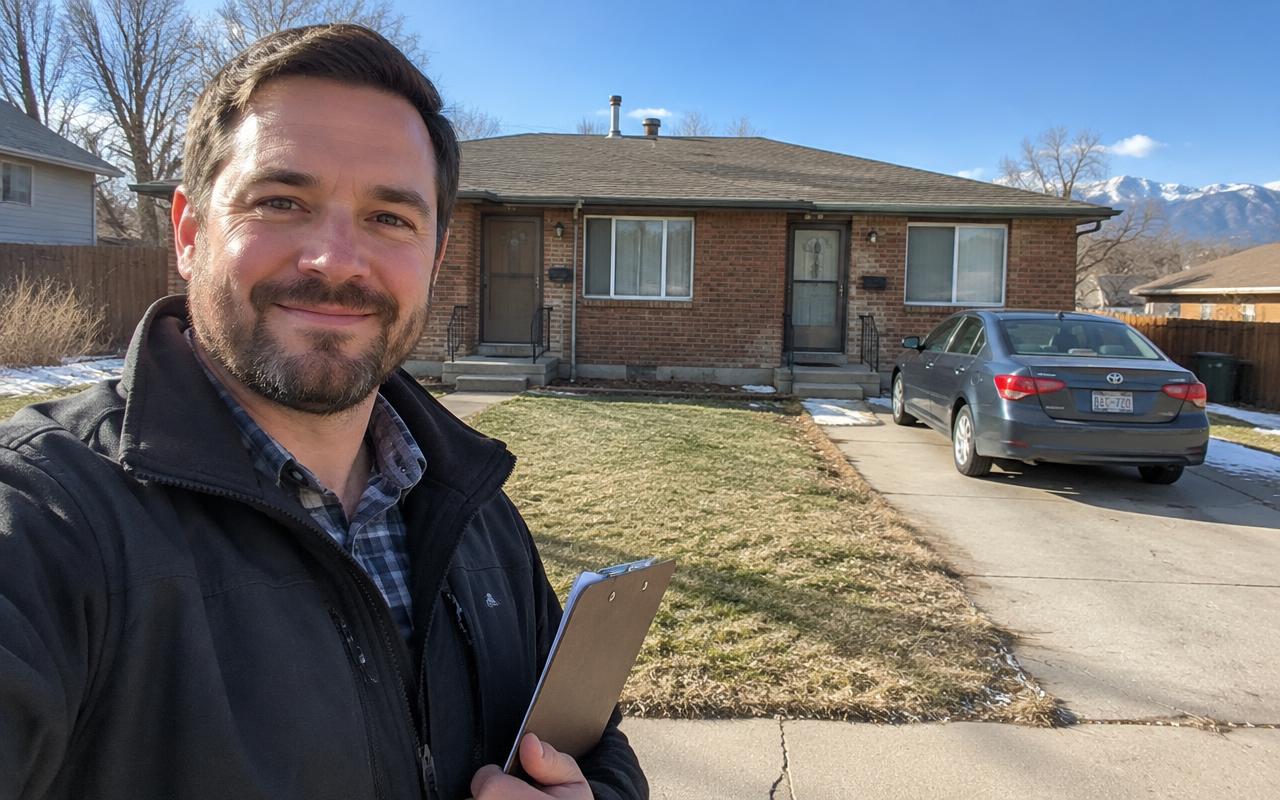
A real estate investor with a clipboard standing in front of a brick Colorado duplex rental property

A DSCR loan is an investment property loan that qualifies on the property's cash flow instead of your personal income. DSCR stands for Debt Service Coverage Ratio: the rent the property collects compared to the full monthly payment on the loan.

If the rent covers the payment, the property qualifies. That single shift is why DSCR loans have become the favorite tool of Colorado investors who are self-employed, write off a lot on paper, or already own a few rentals and want to keep going.

  • Qualified on: the property's rental income versus its payment.
  • Not required: tax returns, W-2s, or debt to income ratio calculations.
  • Best for: investors buying or refinancing 1 to 4 unit rentals, including short-term rentals.

How the DSCR math works

Take the property's full monthly payment, meaning principal, interest, taxes, insurance, and any HOA, and divide it by the monthly rental income. The result is your coverage ratio.

A ratio of 1.0 means the rent exactly covers the payment. Above 1.0, the property throws off positive cash flow, and better ratios earn better pricing. Many lenders will also go below 1.0 for strong borrowers with a larger down payment, which can be the right trade for a fast-appreciating rental.

  • 1.0 or higher: rent covers the full payment, the sweet spot for pricing.
  • Below 1.0: still possible with more down payment or strong reserves.
  • Rental income: confirmed by a signed lease or a market rent appraisal when there is no tenant yet.

What you do not have to do

No tax returns. No W-2s. No letter from your CPA explaining your income. The lender does not calculate a debt to income ratio at all, because personal income is not part of the equation.

For self-employed Colorado investors, this is usually the whole point. Write-offs that lower the income a conventional lender can see simply do not matter here.

  • No tax returns or W-2s to document income.
  • No debt to income ratio limit tied to your personal finances.
  • Close in the name of your LLC or entity in most cases, which conventional loans do not allow.

Who a DSCR loan fits

It fits self-employed investors whose tax returns understate their real income. It fits the second and third rental, where a conventional lender starts counting every mortgage payment against your personal debt to income ratio and eventually says no.

It also fits short-term rental buyers in the mountain towns and along the Front Range: lenders can qualify the property on its Airbnb or VRBO income history, which a conventional loan simply cannot do.

  • Self-employed investors who show very little income on paper.
  • Portfolio landlords scaling past three or four conventional-financed doors.
  • Short-term rental buyers purchasing with the property's booking income.
  • Buyers who want the property titled in an LLC for liability and bookkeeping reasons.

What lenders actually look at

The property, the ratio, and you at a high level. Expect a credit score minimum in the mid 600s, a down payment of 20% to 25% on purchases, and a few months of reserves in the bank after closing.

The property itself gets the scrutiny: appraised value, condition, and its rent potential. That is the trade. Less attention on you, more attention on the deal.

  • 20% to 25% down on most Colorado purchase scenarios.
  • Mid 600s minimum credit score, with better pricing above 700.
  • 3 to 6 months of the payment in reserves after closing.
  • A signed lease or a market rent appraisal to establish income.

DSCR versus a conventional investor loan

A conventional loan on an investment property usually prices higher than a primary residence loan, requires detailed income documentation, counts the full payment against your personal ratios, and cannot vest in an LLC.

A DSCR loan trades a modest pricing premium for all of that friction disappearing. For a borrower with clean, documented income buying their first rental, conventional can still win. For everyone else, and especially for the second rental onward, the DSCR math usually wins outright.

How we help

Because we work with more than 70 wholesale mortgage banks, we shop your DSCR file across the lenders that price it hardest, and the spread between them can be significant. Ratios, reserves, and entity rules vary by lender, so the same property can qualify easily at one bank and get squeezed at another.

Send us the address and the rent, and we will tell you the ratio, the pricing, and the cash you need before you write the offer.

  • You: bring the property address, the rent or booking history, and your down payment plan.
  • Us: run the ratio, price it across our lender network, and structure the vesting.
  • You get: a clear picture of the deal's numbers before you commit.

What investors ask about DSCR loans

The short version of each answer. If yours is not here, call or text 720-386-4071 and ask.

Questions about your own numbers?

Call or text 720-386-4071, or start the application and we will follow up the same day. The conversation is free, and the math is yours to keep.

Chat Now