Condo financing

Condotel Loans in Colorado

A condotel is a condo unit inside a building that runs like a hotel, and the hotel part is exactly what stops most standard loans. That does not mean the unit cannot be financed. It means it needs a lender whose guidelines were written for this building type.

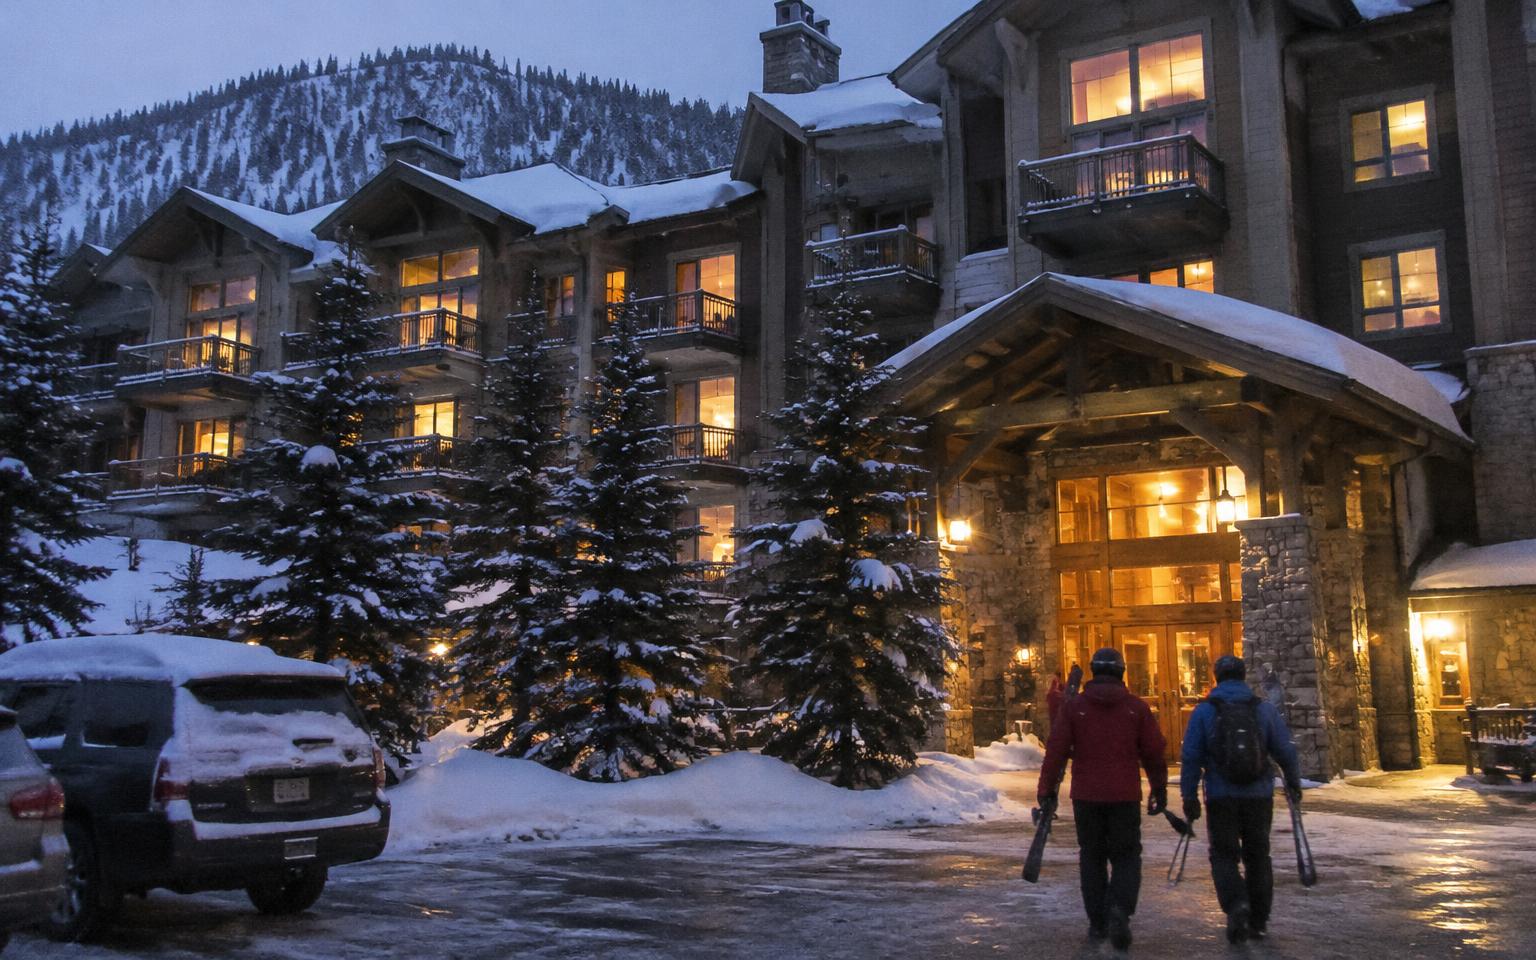
A Colorado mountain resort lodge at winter dusk, snow on the roof and warm light in the windows, two skiers walking toward the entrance

People come to us after a bank has already said no, usually confused, because the unit is beautiful, the price is fair, and their own file is in good shape. Often the decline had nothing to do with them. It was about what the building is.

As a broker we shop wholesale lenders rather than one bank's shelf, and several of them run condotel and specialty resort property programs. We match the unit to a lender whose guidelines cover it.

  • Fannie Mae, Freddie Mac, FHA and VA generally do not finance condotels.
  • Specialty and portfolio lenders do, and that is the path these units take.
  • The recorded documents decide it, not the name on the listing.

What a condotel is

You own the unit, and the property around it operates with hotel services. That combination is what makes the financing different from a normal condo purchase.

  • A front desk and on-site rental management.
  • Nightly rentals, often arranged by the property itself.
  • Housekeeping, linens, and hotel style amenities.
  • A rental program you can join, and in some buildings are required to join.

Why most standard loans don't work

The nightly rental model and the shared hotel operations sit outside agency project rules, so the conventional shelf is closed before your file is even scored. A lender that only sells agency loans will decline the property on sight, with no review of your income or credit.

  • Conventional loans follow agency project standards that exclude most condotel setups.
  • FHA and VA need the project on their approved lists, which condotels rarely are.
  • Banks with no specialty program have nothing to offer, so the answer is no by default.

How we help

Because we work with wholesale mortgage banks rather than a single institution's own products, we can put the file in front of lenders who actually write on condotel units. We match the property to a lender whose guidelines cover the building type, the rental program, and how you intend to use the unit.

  • Second homes in Colorado resort communities.
  • Investment units with an existing rental program.
  • Buyers planning to shift a unit between personal use and rental use.

What to expect

Condotel financing is structured differently from a standard condo loan, and the lender studies the property as closely as it studies you.

  • A larger down payment than a standard condo loan calls for.
  • A higher rate than a conventional condo loan would carry.
  • Lender review of the rental program and the management agreement.
  • Questions about unit size and whether the unit has a full kitchen.
  • HOA or hotel management documents, budgets, and reserve statements.

Colorado condotel markets

Colorado's condotel stock sits mostly in resort towns, and each market carries its own mix of rental programs and ownership rules.

  • Breckenridge, Vail, Beaver Creek, Keystone, and Copper Mountain.
  • Steamboat Springs and Winter Park.
  • Telluride, Aspen, and Snowmass.

Condotel vs. non-warrantable condo

The two terms get used interchangeably, and they are not the same thing. A condotel describes a building type. Non-warrantable describes a condo that misses one of the agency project standards.

  • A condotel usually cannot be financed conventionally at all, because of what the building is.
  • A non-warrantable condo could be financed conventionally, but the project fails one standard.
  • Both point toward portfolio and specialty lenders rather than a big retail bank.
  • Both are worth a second opinion before you assume the answer is no.

Questions about condotel financing

Straight answers to the questions we hear most. If yours is not here, call or text 720-386-4071 and ask.

Questions about your own numbers?

Call or text 720-386-4071, or start the application and we will follow up the same day. The conversation is free, and the math is yours to keep.

Loan programs, terms and availability vary by lender and property and are subject to credit, income, property and project approval. This is not a commitment to lend.

Chat Now